North Shore Market Update: Mortgage Rates Hit 7.40% and Why the Median Is Misleading You
Three numbers landed this week that every North Shore buyer and seller should see together, because apart they tell three different and slightly misleading stories.
Mortgage rates hit their highest level in roughly three years. The Hamptons median sale price fell more than six percent. And nationally, sellers are cutting prices at a rate we have not seen in a September since 2018. Read any one of those on its own and you would reach the wrong conclusion about what is happening in Huntington, Lloyd Harbor, Cold Spring Harbor or Dix Hills.
Here is what actually happened, and what it means if you are buying or selling here this fall.
Borrowing costs jumped, and fast
Freddie Mac put the average 30 year fixed mortgage at 7.40% on October 8, up from 7.28% the week before. A year ago that same number was 6.30%.
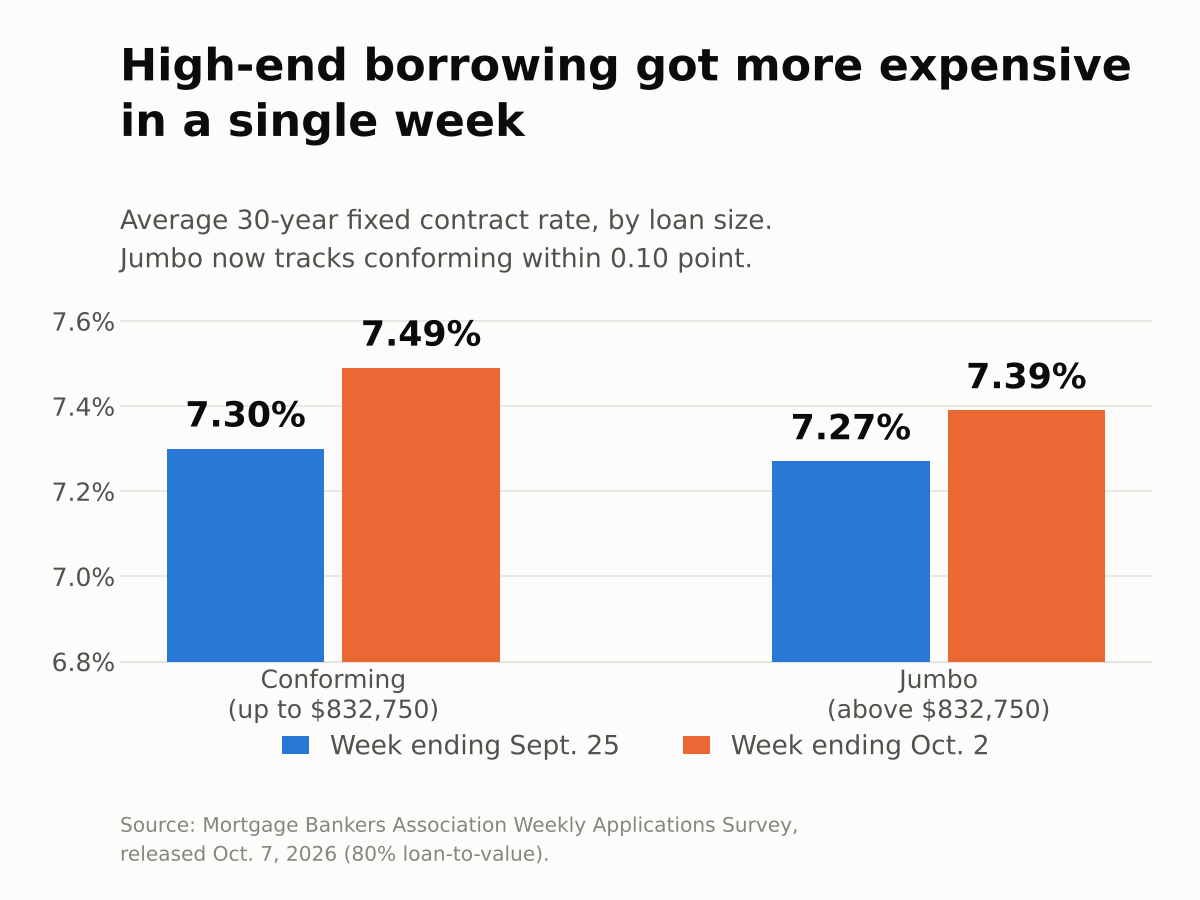
The Mortgage Bankers Association, which breaks the market into conforming and jumbo loans, showed an even sharper one week move. Conforming 30 year rates went to 7.49% from 7.30%. Jumbo loans went to 7.39% from 7.27%.
The cause sits in the bond market rather than in housing. The 10 year Treasury yield pushed above 5.35% on October 7, its highest level since 2002, with the 30 year Treasury at 5.70%. Mortgage rates are priced off those long term yields, so when they move, we feel it within days. The Federal Reserve raised its benchmark rate in September and officials project roughly one more increase, a very different environment from the one buyers were promised a year ago.
The takeaway is that waiting for rates to fall is no longer a strategy. It is a bet against the direction the bond market is currently moving.
What that costs at North Shore price points
This is where the national headline stops being useful, because of one number almost nobody mentions: the conforming loan limit is $832,750.
Long Island's median sale price just set a record at $782,000. The median sale on this island is already brushing the jumbo threshold. At the price points we work in on the North Shore, essentially every financed buyer is a jumbo buyer. So the jumbo rate is the number to watch, not the headline rate you see on the news.
Two things follow from that.
First, the familiar jumbo discount has largely disappeared. Jumbo and conforming are now pricing within about a tenth of a point of each other. Loan size is no longer what drives your rate. The lender, the relationship and the strength of the asset are.
Second, the year over year move is substantial once you put it on a real loan. On a $1.4 million mortgage, going from 6.30% a year ago to 7.40% today works out to roughly $1,000 more per month, or about $12,000 a year, by my calculation on those published rates. That is not a rounding error. That is a kitchen renovation, every year, for the life of the loan.
If you are financing a purchase here, get quotes from more than one lender. Freddie Mac's own chief economist made exactly that point this week, noting that multiple quotes can save borrowers thousands over the life of a loan.
Why the median is lying to you
Jonathan Miller's third quarter reports for our region came out this week, and they are a useful lesson in how to read market data.
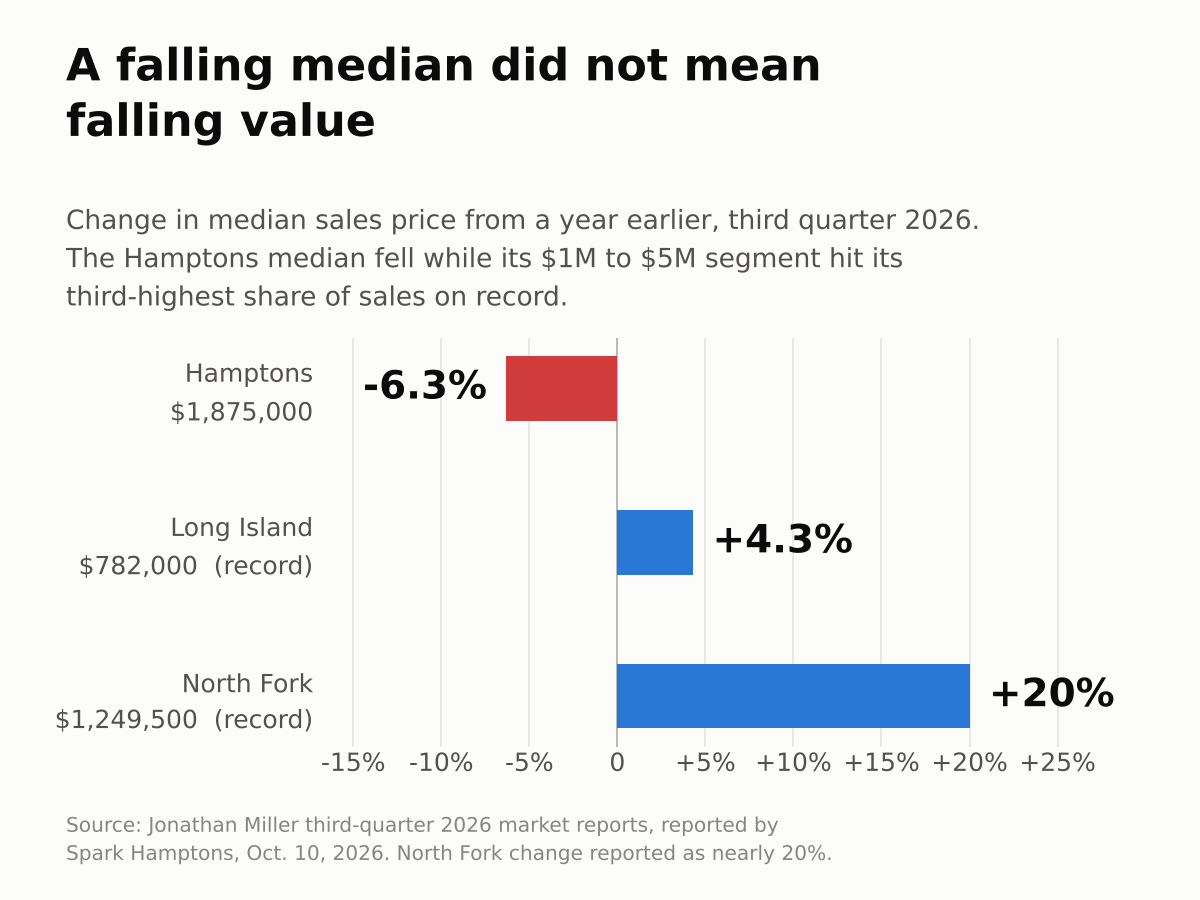
The Hamptons median sale price fell 6.3% to $1,875,000. In the very same quarter, the North Fork median rose nearly 20% to an all time high of $1,249,500, and Long Island posted a record $782,000, up 4.3%.
Three neighboring markets, one economy, three different directions. That is not a contradiction. It is arithmetic.
A median is simply the middle sale. It moves when the mix of what closes changes, not necessarily when values change. In the Hamptons, homes between $1 million and $5 million made up 65.5% of sales, the third highest share on record. More closings concentrated in that band pull the middle number down even when individual homes are holding or gaining. Meanwhile, at the very top of that market, above $6,625,000, prices rose almost twice as fast as the broader market.
I see the same distortion here on the North Shore. A quarter in which several large estates close in Lloyd Harbor or Huntington Bay lifts the median. A quiet quarter at the top drops it. Neither number tells you what your house is worth.
What tells you is recent comparable sales of genuinely similar homes, adjusted for condition, acreage and water frontage. There is no headline that substitutes for it.
The national buyer's market has not arrived here
Nationally, September was a difficult month for sellers. Realtor.com data reported this week shows 20.8% of listings took a price cut, the highest September share since 2018. Active listings reached 1,161,615, bringing inventory within 9.1% of typical pre-pandemic levels. Homes under contract fell 4.1%. Redfin counted seller concessions in 44.7% of August sales. In 43 of the 50 largest metros, there were more homes for sale than a year earlier.
Now look at our market. Miller's third quarter report counted 5,053 listings across Long Island, roughly 36% below the normal third quarter of the past decade. More than half of sales involved a bidding war. The median set another record, the eighth consecutive quarter to do so.
Both sets of numbers are accurate. They simply describe different markets.
The consequence shows up in my conversations every week. A buyer relocating from a metro where listings have piled up arrives expecting to open well under asking and wait out the seller. Meanwhile a Huntington homeowner reads that price cuts have hit a yearly high and wonders whether they missed their window. Both are reasoning from the wrong map.
What to actually do this fall
If you are selling: scarcity is still working in your favor, but it does not make pricing automatic. Higher rates have thinned the pool of financed buyers, and the ones left are more sensitive to monthly payment than they were a year ago. Price to the comparables rather than the record headline and you will still see competitive activity.
If you are buying: do not wait for a rate the bond market is not currently offering. Lock when the number works for your budget, shop at least three lenders including a portfolio lender who holds jumbo loans, and understand that in this inventory environment the right house will not sit while you deliberate.
Find out what your North Shore home is worth
Medians are built from whatever happened to sell. Your home is not a median. If you own in Huntington, Lloyd Harbor, Cold Spring Harbor, Centerport, Northport, Huntington Bay or Dix Hills and you want a clear answer grounded in recent comparable sales rather than a headline, I am happy to put one together for you.
Request a comparable based home valuation, or reach out directly and we can talk through what your specific block and price point are doing right now.
Joe Maselli is a Licensed Real Estate Broker and the owner of JMRENY / Joe Maselli Real Estate, 52 Broadway Suite 1, Greenlawn, NY 11740, serving the North Shore of Long Island.
Sources: Freddie Mac Primary Mortgage Market Survey, October 8, 2026. Mortgage Bankers Association Weekly Applications Survey, October 7, 2026, covering the week ending October 2. Jonathan Miller's third quarter 2026 market reports, reported by Spark Hamptons, October 10, 2026. Realtor.com September 2026 housing report, reported by RISMedia, October 7, 2026. Treasury yield figures as reported by Forbes, October 7, 2026. Payment comparison is the author's calculation based on the published rates.
Categories
Recent Posts


Broker Associate/Office Owner License ID: 10301221065
+1(516) 253-1113 | jmaselli@jmreny.com